November 15, 2026
Weekly Market Outlook
By Geoff Bysshe
Last week’s news flow was so flooded with reporting on the fall of Jenson Huang that it was easy to miss the news that will likely be more important in driving the broader market direction over the coming months.
With the coming months being some of the most seasonally bullish, you don't want your focus on market factors to be distracted by scandals.
Not to mention that during these next few months we’re likely to see compelling evidence of what we described as the “changed game” in last week’s Market Outlook, “The AI Bull Market Isn't Over. The Game Has Changed.”
In fact, the fall of the man who could be considered the most influential person in accelerating the AI infrastructure build-out will likely increase the importance of the next phase of the AI race.
Remarkably, markets were quick to figure this out last week. As always, insight into what will happen next wasn’t in the news, but in the markets’ reactions.
Additionally, while stocks have been focused on the midterm elections and the fall of Jenson Huang, the bonds, currency, and energy markets have been making historically significant and potentially market-impactful moves which seem to be underappreciated by the current market narrative.
These moves are likely to provide headwinds and tailwinds to the stocks and sectors likely to lead the market in a post Jenson Huang world.
Despite The Fall From Grace by both SMH and Jenson, Stocks Rallied Last Week
As you can see from the table below, the majority of sectors and all major US stock indexes rallied last week, despite what felt like a very bearish news flow.
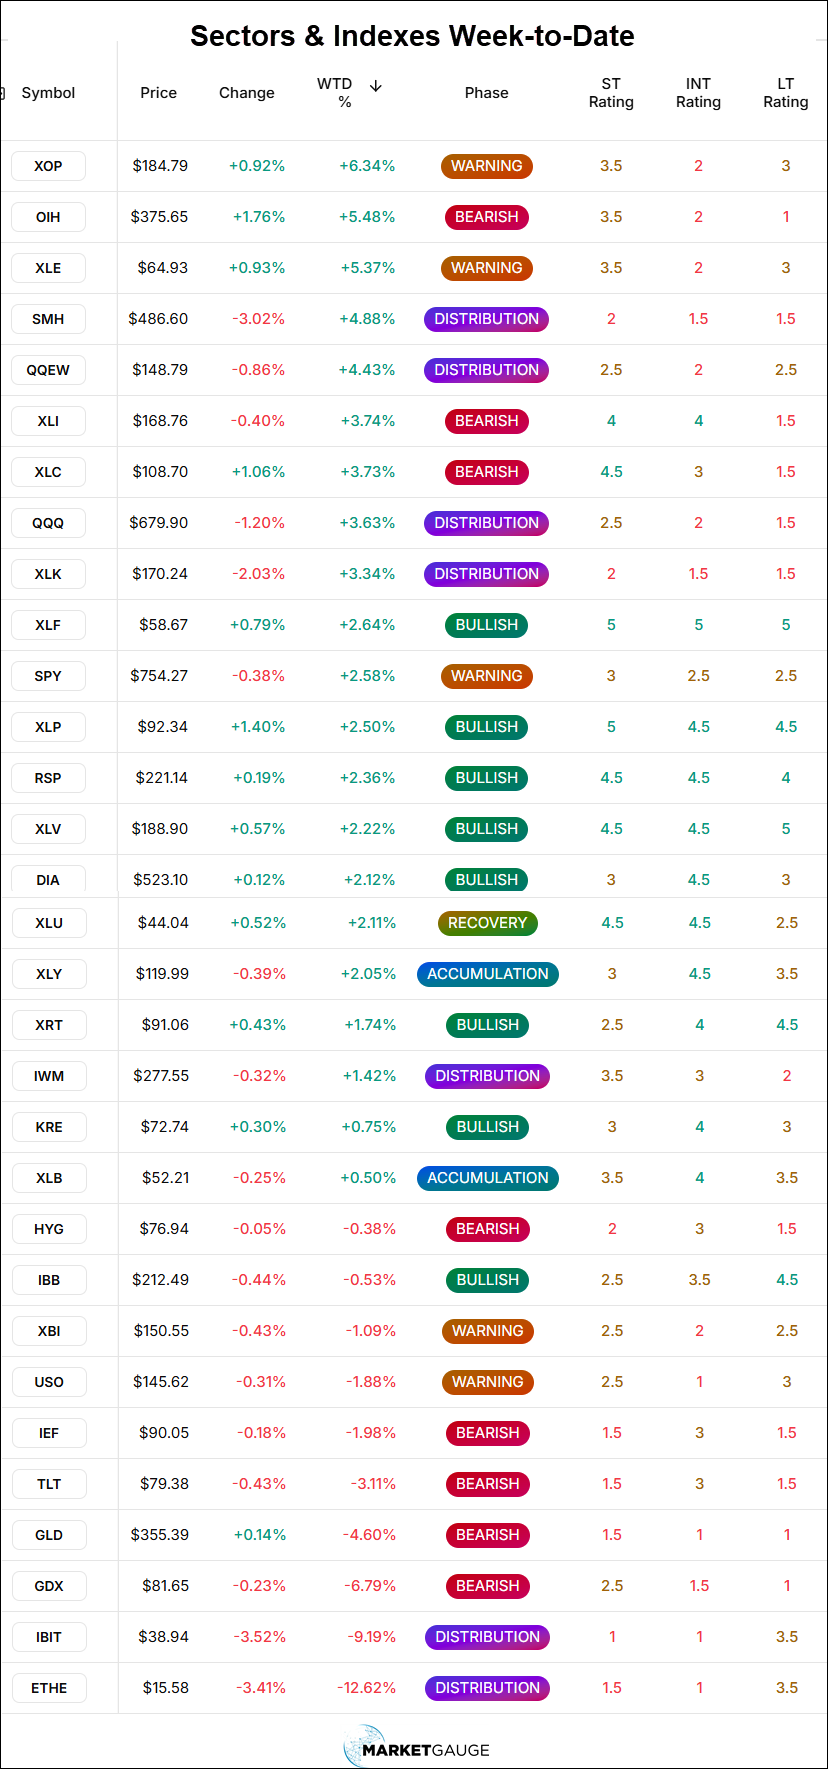
Perhaps most impressive is the fact that SMH rallied almost 5% while its largest component, NVDIA collapsed 12% for the week.
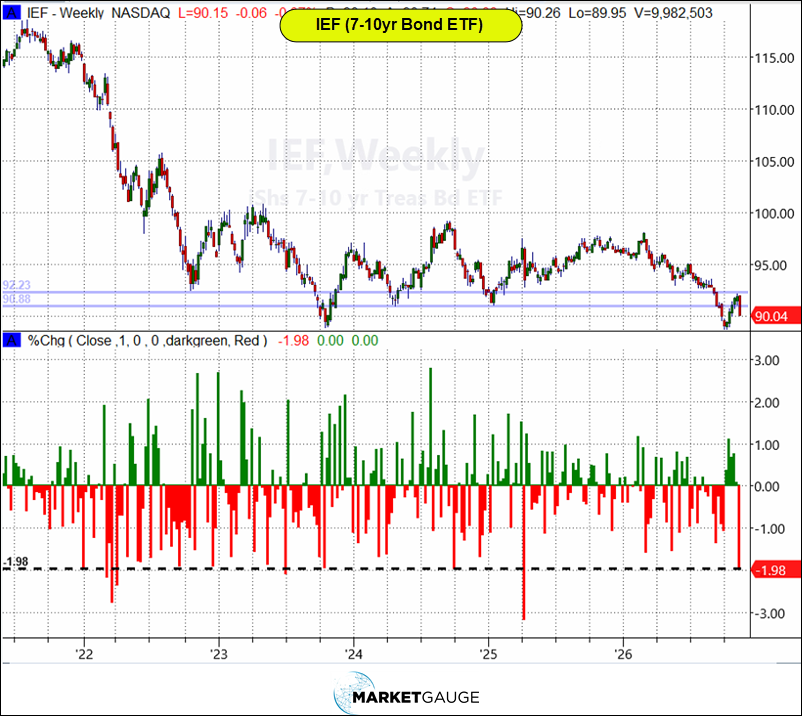
Additionally, bonds had a historically bearish week (see chart below), and the major equity indexes shrugged it off and posted over 1% gains even by the rate sensitive IWM.
Finally, the US Dollar Index crossed a major milestone (see chart below), which historically has led to significant moves higher.
 |
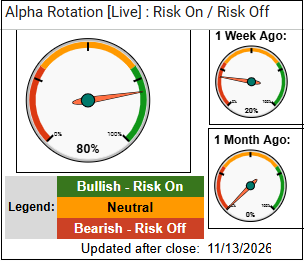 Every week we review the big picture of the market's technical condition as seen through the lens of our Big View data charts. The bullets provide a quick summary organized by conditions we see as being risk-on, risk-off, or neutral. The video analysis dives deeper. |
Summary: U.S. equities rebounded strongly this week, supported by broad sector participation, strengthening risk gauges, and favorable seasonal trends, though small caps and semiconductors remain technically weak. Despite these encouraging signs, mixed market internals, persistent growth-stock weakness, elevated volatility, and deteriorating trends in international equities, bonds, and Bitcoin suggest the recovery remains fragile and warrants a cautious approach.
Risk On
Neutral
Risk Off
Maintain a cautiously optimistic approach as improving market breadth, stronger risk gauges, and favorable seasonal trends support the potential for a continued year-end rally. Look for selective buying opportunities in sectors and stocks demonstrating relative strength, particularly value-oriented areas, while remaining cautious on growth, semiconductors, and small caps until they reclaim key moving averages. Favor incremental position sizing and avoid aggressively increasing exposure until market internals, volume patterns, and volatility confirm the recovery. Maintain appropriate cash reserves, use disciplined stops to manage downside risk, and be prepared to increase exposure if the major indexes reclaim their 50-Day Moving Averages and broader market participation continues to improve.
**There is no video this week.
Every week you'll gain actionable insight with: