October 4, 2026
Weekly Market Outlook
By Geoff Bysshe
It’s been all too common to read that “stocks ignored the bearish move in bonds.”
While that's been true at times, the bigger picture doesn’t support it, and ignoring it could be costly.
The cost could come from both being in the wrong trade or missing the opportunity to enter new trades early as they are developing.
This week we’ll look at the effect bonds have had on stocks and an investment theme that's looking promising after being pulled down by the bear market – in stocks.
This week’s Outlook is another example of the quote shared a few weeks ago,
“It ain’t what you don’t know that gets you into trouble.
It’s what you know for sure that just ain’t so.”
- Mark Twain
There’s Nothing Stealth About This Bear Market
The S&P 500 is up about 13% for the year, and about only 32% of the 500 stocks are outperforming the index
The Equal Weighted S&P 500 ETF (RSP) is up about 9.5%, and about 38% of stocks in the index are outperforming it.
On the bearish side of the index, however:
While the year-to-date numbers are discouraging, the bear market worth focusing on isn’t measured year-to-date.
The trend to focus on is the increasing pressure that higher interest rates are having on the broad market.
In the chart below, you can see that TLT has had a stair-step decline in price, which represents the increase in rates. At the same time, the SPY index has managed to work its way higher when the TLT rallies or goes sideways, but the percentage of stocks staying above their 50-day (blue) and 200-day moving averages (green) has been accelerating lower.
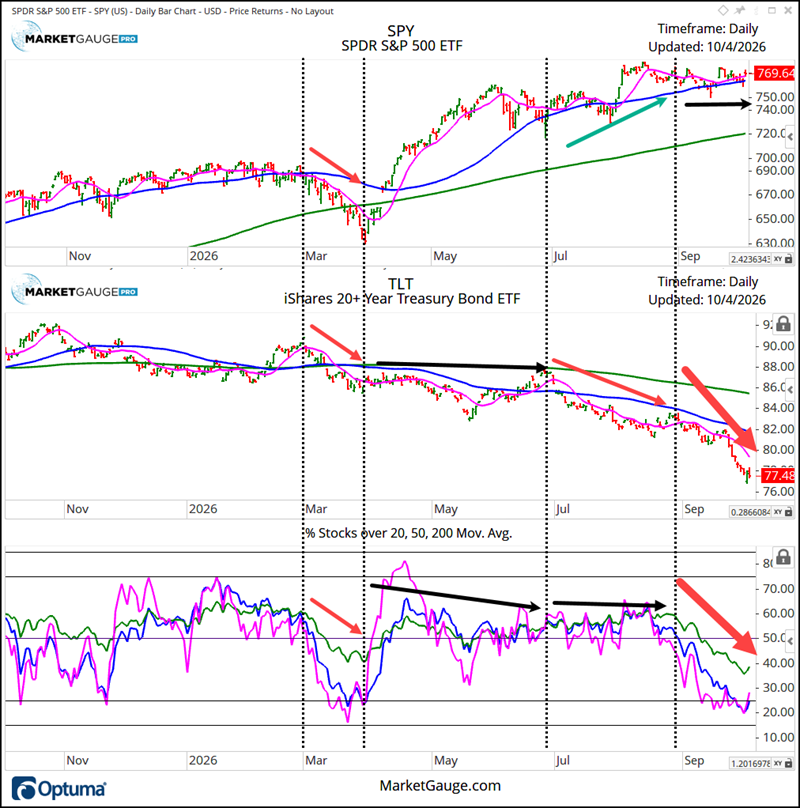
It’s clear that the last push lower in TLT (move higher in rates) has had an increasingly bearish impact on S&P 500 stocks trying to stay above key moving averages, which means they are going down.
The Indexes Are Near All-Time Highs. Will The Broad Market Follow?
**The commentary will be completed later tonight.
 |
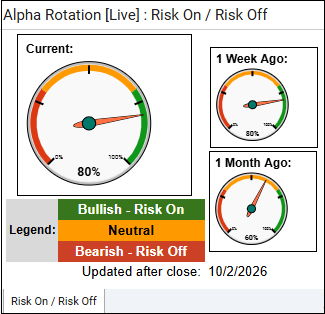 Every week we review the big picture of the market's technical condition as seen through the lens of our Big View data charts. The bullets provide a quick summary organized by conditions we see as being risk-on, risk-off, or neutral. The video analysis dives deeper. |
Summary: Markets remain broadly risk-on, led by new highs in the Nasdaq and semiconductors, low volatility, strong risk gauges, and slightly improving breadth and internals. However, weak sector participation, deteriorating longer-term breadth, and a sharp rise in rates remain significant concerns beneath the strength in growth and technology.
Risk On
Neutral
Risk Off
Maintain a risk-on bias but stay selective, favoring technology, semiconductors, and other areas demonstrating clear relative strength while allowing winning positions to run. With participation still uneven and rates moving sharply higher, avoid aggressively expanding exposure until broader sectors and longer-term breadth improve; keep some cash available and use weakness in leading areas for measured entries rather than chasing new highs.
Continue to monitor QQQ and semiconductor leadership, market breadth, and the bond/rate move for confirmation or deterioration. Add exposure if improving internals broaden into more sectors, but reduce risk if technology leadership breaks, breadth rolls back over, or rising rates begin to pressure the major indexes more broadly.
**This is today’s video. Please note that the date shown on the title slide is incorrect.**
Every week you'll gain actionable insight with: